The largest PE-backed MGA platforms collectively manage over 150 programs and billions in premium: K2, Doxa, Novacore, Baldwin/MSI, Bishop Street. As of today, none has acquired an AI-native platform – one that uses machine learning or AI as the core of its underwriting, operations, or claims.
This is one market running on two distinct tracks, with different talent, different technology, different capital, different access to capacity.
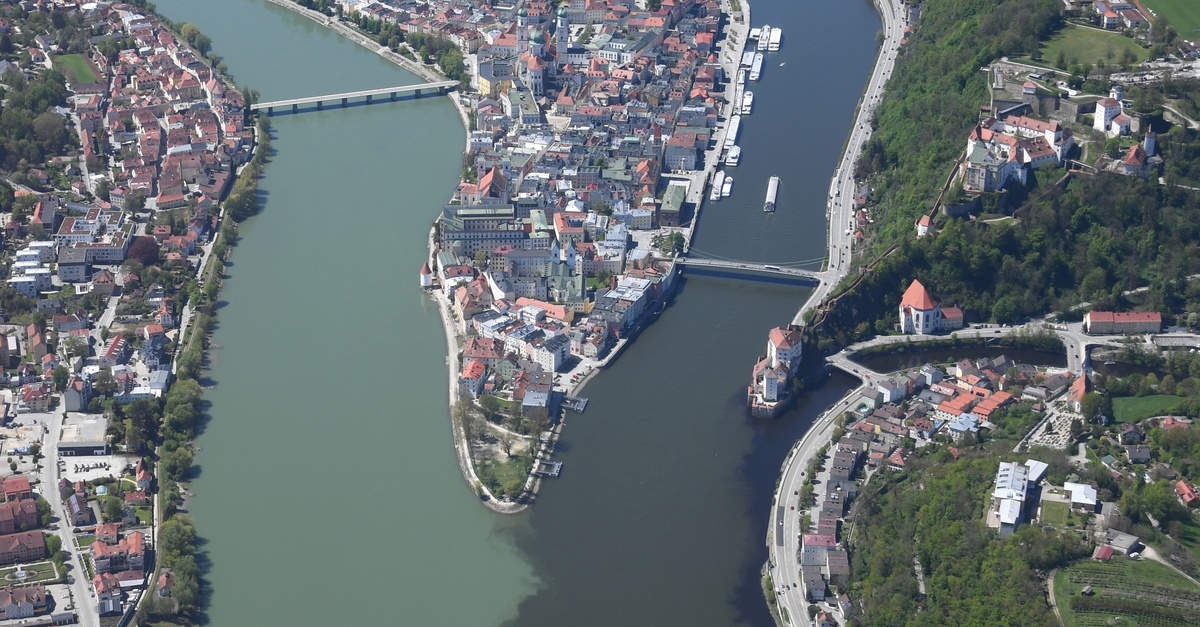
Passau, Germany -- where the Danube, Inn, and Ilz converge. Photo: Carsten Steger / Wikimedia Commons (CC BY-SA 4.0)
The traditional track
A PE platform acquires an MGA with an experienced underwriting team and a proven book, adds shared infrastructure (compliance, carrier relationships, technology, analytics, …), and compounds returns through operating leverage. K2, backed by Warburg Pincus, reports 36 programs and approximately $2 billion in premium. Doxa, backed by Goldman Sachs Asset Management, manages 40+ programs and has crossed $1.2B. Acquisitions typically price at 12 - 15x EBITDA, with outliers reaching 20x for exceptional books. The model works, but it is narrow.
The AI-native track
And then there is the AI-native MGA. AI changes what programs can do: serve accounts that were too small to underwrite profitably, cover risks where the traditional loss data doesn’t exist, and bundle risk mitigation services alongside the policy that used to require a separate vendor.
Neptune Flood has the most impressive model in this space. Zero human underwriters. Its ML engine handles risk selection, pricing, concentration control, and carrier allocation. A lifetime loss ratio of 25% across 21 landfall hurricanes since 2018. For comparison, NFIP’s loss ratio was 86% over the same period.
Coalition, Inc. redefined cyber insurance. Their “active insurance” approach – monitoring networks and intervening before a breach – changed the meaning of a cyber policy. Nirvana Insurance trains its trucking fleet insurance models on 30 billion miles of telematics data.
AI-native MGAs share a common talent model that looks different from the traditional side: a tech founder paired with an insurance veteran (typically in that order). The tech founder builds the platform. The insurance veteran configures the underwriting models and gets the carrier to allocate paper.
Risk-model MGAs
In these programs, the algorithm is the underwriting. A carrier evaluating Neptune is not delegating to an experienced team. It is delegating to a machine. Flood is a data-rich, modellable peril with decades of NFIP history and established cat modeling infrastructure. Does that proof extend to cyber, trucking, or casualty – lines where the data is thinner and the loss patterns less stable? That’s a question reinsurers should keep asking.
Their moat is proprietary data combined with claims outcomes. Neptune’s hurricane loss experience. Nirvana’s telematics mapped to specific driving behaviors and claims. Coalition’s threat signals linked to claims frequency. ML frameworks are commodity infrastructure. The data underneath them – claims outcomes tied to specific underwriting decisions – only comes from running the book. More policies, more claims data, sharper models. That is a flywheel that deserves its name.
Capacity providers need more than a headline loss ratio. They need to see how specific vintages are developing and whether reserves are holding up. I’m not sure a reinsurer can evaluate these programs the way it would evaluate a traditional underwriting team. The model underneath remains a black box with a strong track record. Is that enough?
Workflow MGAs
The second category of AI-native MGAs are workflow programs. These keep the human underwriter but change the economics around them. Shepherd, for example, automates intake, analysis, and pricing for construction risk (a class with heavy submission requirements); Comeryx launched this week to do the same for small-business artisan contractors.
Workflow automation delivers quick ROI. But efficiency gains are replicable – the first thing AI delivers and the last thing that stays proprietary. Any carrier or PE platform with decent engineering can build submission triage and document ingestion. For anyone evaluating a workflow program, the diligence question shifts: you are buying a cost structure and a distribution channel. That compresses the multiple.
Different valuations, different value propositions
Valuation alone tells you these are different markets, but that’s only half the story.
PE platforms create value by adding the infrastructure that smaller programs can’t build on their own: carrier relationships, technology, data, compliance, … I’ve seen MGAs spend most of their time building infrastructure instead of writing business. AI-native programs built all of it before their first policy. The PE value proposition doesn’t land.
And the VC valuations may not hold up to scrutiny. Munich Re acquired At-Bay for $575M, less than half of At-Bay’s $1.35 billion valuation from its last funding round in 2021. Neptune’s IPO priced at roughly $2.8 billion and now trades at about $4 billion. Coalition ($5 billion) and Nirvana ($1.5 billion) haven’t been tested by a public market or an acquisition bid. When they are, the At-Bay discount is the precedent to watch.
Different ways to get capacity
AI-native programs also built a different capacity pipeline. What keeps showing up is the carrier-as-investor: the capacity provider takes an equity stake alongside its paper.
Intact Financial leads Shepherd’s $42M Series B and provides paper. RLI provides capacity to Kettle (wildfire) and holds equity. SiriusPoint is both lead carrier and strategic investor for Honeycomb (habitational property, $275M GWP). Allianz locked in an exclusive deal with Coalition, taking equity and a board seat alongside capacity.
Carriers are buying access to AI-native underwriting capability they can’t build internally. The equity stake aligns incentives in a way traditional fronting doesn’t. If the program works, the carrier benefits twice: underwriting returns and investment returns. If it doesn’t, the carrier has at least a seat at the table and can respond quickly.
The risk is that equity and underwriting create conflicting incentives. When loss ratios deteriorate, underwriting discipline should say non-renew. The equity stake says give them another year. I ran a cyber MGA on Lloyd’s paper. Getting capacity took months. Referrals took days. Bordereaux reporting was standard data, sent monthly. Carrier-as-investor promises a different relationship. Whether it resolves the tension between underwriting discipline and equity interest is something the market hasn’t tested.
Where the two tracks converge
Munich Re’s acquisition of At-Bay follows a sequence: reinsure, invest, acquire (I covered six carrier-MGA deals in detail last month). Other carriers investing alongside capacity are earlier in the same sequence. Carrier-as-investor is a stepping stone to carrier-as-acquirer.
Coalition acquired its own admitted carrier in 2022. MGT acquired a carrier in 2023 and built its AI underwriting platform on a licensed balance sheet – profitable within two years. Corgi started as a risk retention group in 2024 and launched an admitted carrier in August.
For MGAs that stay on fronting paper, convergence will run through the carriers providing it. A carrier that has been reinsuring a program for three years already has its own loss data on the book. A PE firm doing diligence from the outside wants five years of loss development and renewal retention by cohort. AI-native programs can’t hand that over. PE platforms aren’t locked out permanently. But they need to move before the best programs get acquired by their carriers.
The correction ahead
AI-native programs face a different constraint: proving their loss ratios will survive a full market cycle. The fee stack in the traditional model takes 35 cents of every premium dollar before a claim is paid (I described the economics in The Cost of Disassembly). The capital provider’s margin depends on loss ratios staying in the low-50s or below. When loss ratios rise, that margin disappears first on the traditional side. On the AI-native side: do the models that produced strong results in a benign period hold up under stress?
For cyber, industry loss ratios climbed to 53% in 2025 (AM Best), crossing the 50% threshold for the first time since the ransomware surge of 2020-2021. Commercial auto and trucking has posted an underwriting loss for 14 years (AM Best), with a combined ratio of 107 (2024).
Trucking is the line I’d watch most closely. Years of industry losses and no disclosed loss ratio from the most prominent AI-native entrant.
Neptune’s 25% loss ratio is a real data point, reported in their S-1. It is also the only published underwriting result from any AI-native MGA that I’m aware of. Coalition claims 73% fewer claims than the industry average, but hasn’t published a loss ratio. Nirvana says “top decile.” When you’ve run an MGA, you know what to disclose: the numbers that look good. The numbers that don’t get published are the ones capacity providers should ask about.
My take: losses will eventually rise. Rates will harden for cyber, trucking, and professional liability, among others. Three things I’ll be watching. Will Neptune disclose more than the lifetime headline – specifically accident-year development? Will any carrier-invested MGA publish how it responds when the book deteriorates: restructure terms, pull capacity, or ride it out? And will a PE platform acquire its first AI-native program, and at what price?
Two markets, for now
The carriers investing alongside capacity today are building the acquisition pipeline for the future. The reinsure-invest-acquire playbook is already running. PE platforms that don’t develop a similar AI-native acquisition strategy will find themselves holding the slower-growing part of the market.
Carriers reviewing MGAs have always asked for loss triangles, renewal retention, team tenure. But these questions only make sense for programs underwritten by humans. Most carriers haven’t figured out how to diligence an AI model. The ones investing alongside capacity are learning by sitting inside the book.
The real value of the equity stake isn't the return - it's the visibility.
How long both tracks will run in parallel depends on the loss ratios. The cycle will sort the programs that work from the ones that don’t. Anyone waiting for the loss data to be published is already behind.
This is the third article in my MGA economics series. The first, What Gets Lost in the MGA Assembly Line, examines the accountability gaps in the disassembled value chain. The second, The Cost of Disassembly, breaks down the fee stack.